Compute Wavelet Cross-Covariance Between Two Time Series
spin.covariance.RdComputes wavelet cross-covariance or cross-correlation between two time series.
spin.covariance(x, y, lag.max = NA)

spin.correlation(x, y, lag.max = NA)
Arguments
Value
List structure holding the wavelet cross-covariances (correlations) according to scale.
Details
See references.
References
Gencay, R., F. Selcuk and B. Whitcher (2001) An Introduction to Wavelets and Other Filtering Methods in Finance and Economics, Academic Press.
Whitcher, B., P. Guttorp and D. B. Percival (2000) Wavelet analysis of covariance with application to atmospheric time series, Journal of Geophysical Research, 105, No. D11, 14,941-14,962.
See also
Examples
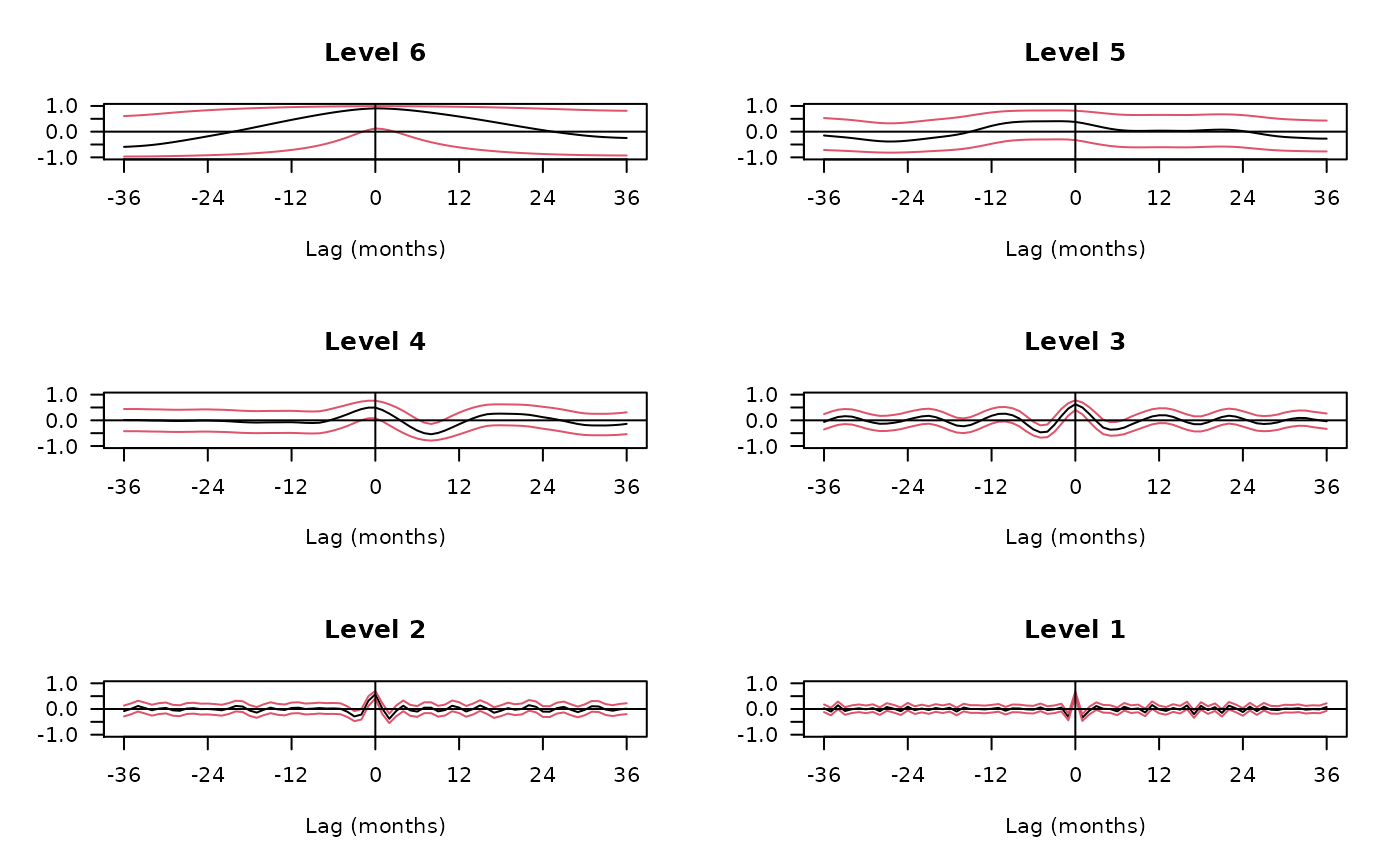
## Figure 7.9 from Gencay, Selcuk and Whitcher (2001)
data(exchange)
returns <- diff(log(exchange))
returns <- ts(returns, start=1970, freq=12)
wf <- "d4"
demusd.modwt <- modwt(returns[,"DEM.USD"], wf, 8)
demusd.modwt.bw <- brick.wall(demusd.modwt, wf)
jpyusd.modwt <- modwt(returns[,"JPY.USD"], wf, 8)
jpyusd.modwt.bw <- brick.wall(jpyusd.modwt, wf)
n <- dim(returns)[1]
J <- 6
lmax <- 36
returns.cross.cor <- NULL
for(i in 1:J) {
  blah <- spin.correlation(demusd.modwt.bw[[i]], jpyusd.modwt.bw[[i]], lmax)
  returns.cross.cor <- cbind(returns.cross.cor, blah)
}
returns.cross.cor <- ts(as.matrix(returns.cross.cor), start=-36, freq=1)
dimnames(returns.cross.cor) <- list(NULL, paste("Level", 1:J))
lags <- length(-lmax:lmax)
lower.ci <- tanh(atanh(returns.cross.cor) - qnorm(0.975) /
                 sqrt(matrix(trunc(n/2^(1:J)), nrow=lags, ncol=J, byrow=TRUE)
                      - 3))
upper.ci <- tanh(atanh(returns.cross.cor) + qnorm(0.975) /
                 sqrt(matrix(trunc(n/2^(1:J)), nrow=lags, ncol=J, byrow=TRUE)
                      - 3))
par(mfrow=c(3,2), las=1, pty="m", mar=c(5,4,4,2)+.1)
for(i in J:1) {
  plot(returns.cross.cor[,i], ylim=c(-1,1), xaxt="n", xlab="Lag (months)",
       ylab="", main=dimnames(returns.cross.cor)[[2]][i])
  axis(side=1, at=seq(-36, 36, by=12))
  lines(lower.ci[,i], lty=1, col=2)
  lines(upper.ci[,i], lty=1, col=2)
  abline(h=0,v=0)
}