Discrete Wavelet Transform (DWT)
dwt.RdThis function performs a level \(J\) decomposition of the input vector or time series using the pyramid algorithm (Mallat 1989).
dwt(x, wf = "la8", n.levels = 4, boundary = "periodic")

dwt.nondyadic(x)

idwt(y)
Arguments
- x
a vector or time series containing the data be to decomposed. This must be a dyadic length vector (power of 2).
- wf
Name of the wavelet filter to use in the decomposition. By default this is set to
"la8", the Daubechies orthonormal compactly supported wavelet of length L=8 (Daubechies, 1992), least asymmetric family.- n.levels
Specifies the depth of the decomposition. This must be a number less than or equal to log(length(x),2).
- boundary
Character string specifying the boundary condition. If
boundary=="periodic"the default, then the vector you decompose is assumed to be periodic on its defined interval,
ifboundary=="reflection", the vector beyond its boundaries is assumed to be a symmetric reflection of itself.- y
An object of S3 class
dwt.
Value
Basically, a list with the following components
- d?
Wavelet coefficient vectors.
- s?
Scaling coefficient vector.
- wavelet
Name of the wavelet filter used.
- boundary
How the boundaries were handled.
Details
The code implements the one-dimensional DWT using the pyramid algorithm (Mallat, 1989). The actual transform is performed in C using pseudocode from Percival and Walden (2001). That means convolutions, not inner products, are used to apply the wavelet filters.
For a non-dyadic length vector or time series, dwt.nondyadic pads
with zeros, performs the orthonormal DWT on this dyadic length series and
then truncates the wavelet coefficient vectors appropriately.
References
Daubechies, I. (1992) Ten Lectures on Wavelets, CBMS-NSF Regional Conference Series in Applied Mathematics, SIAM: Philadelphia.
Gencay, R., F. Selcuk and B. Whitcher (2001) An Introduction to Wavelets and Other Filtering Methods in Finance and Economics, Academic Press.
Mallat, S. G. (1989) A theory for multiresolution signal decomposition: the wavelet representation, IEEE Transactions on Pattern Analysis and Machine Intelligence, 11(7), 674–693.
Percival, D. B. and A. T. Walden (2000) Wavelet Methods for Time Series Analysis, Cambridge University Press.
Examples
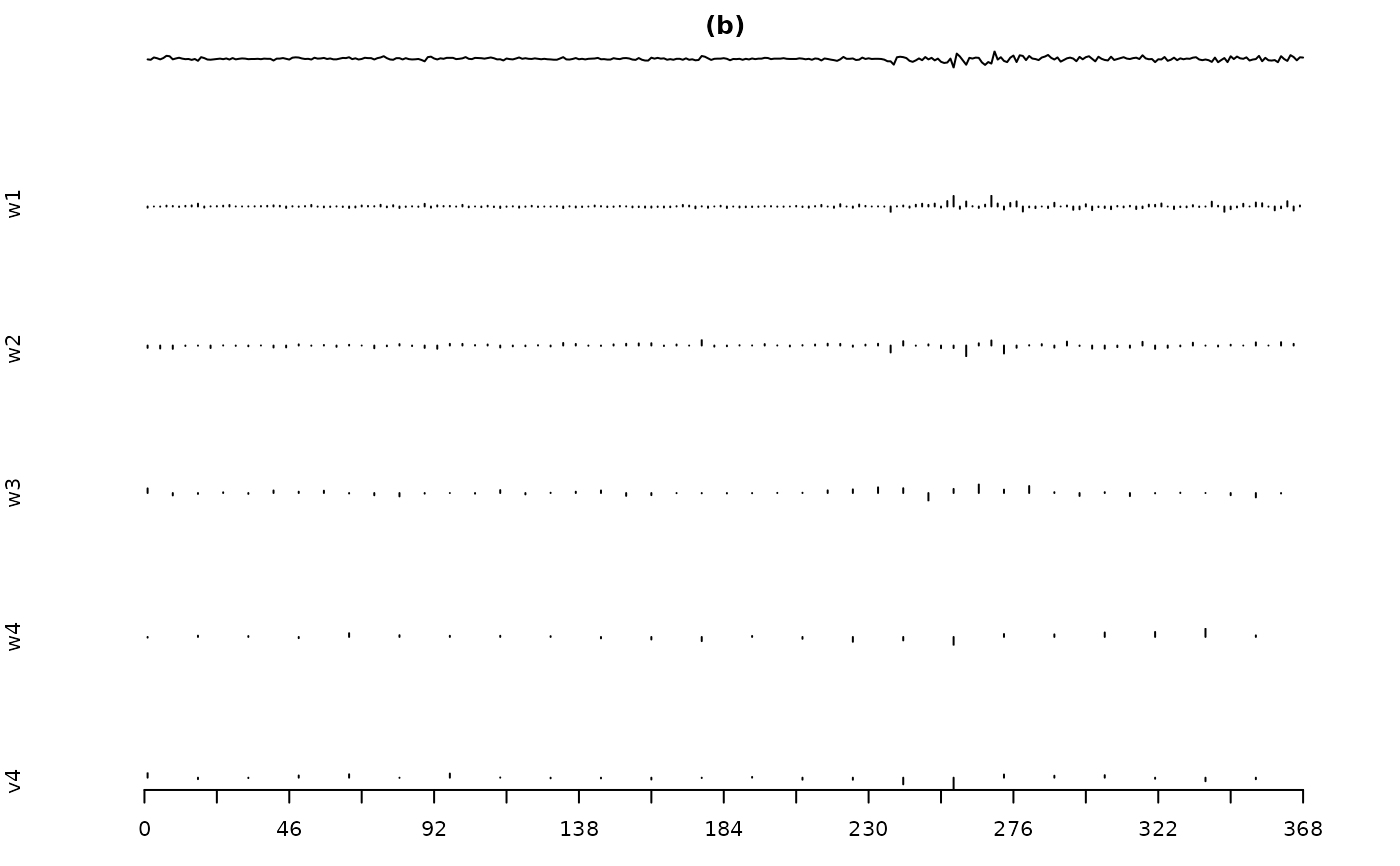
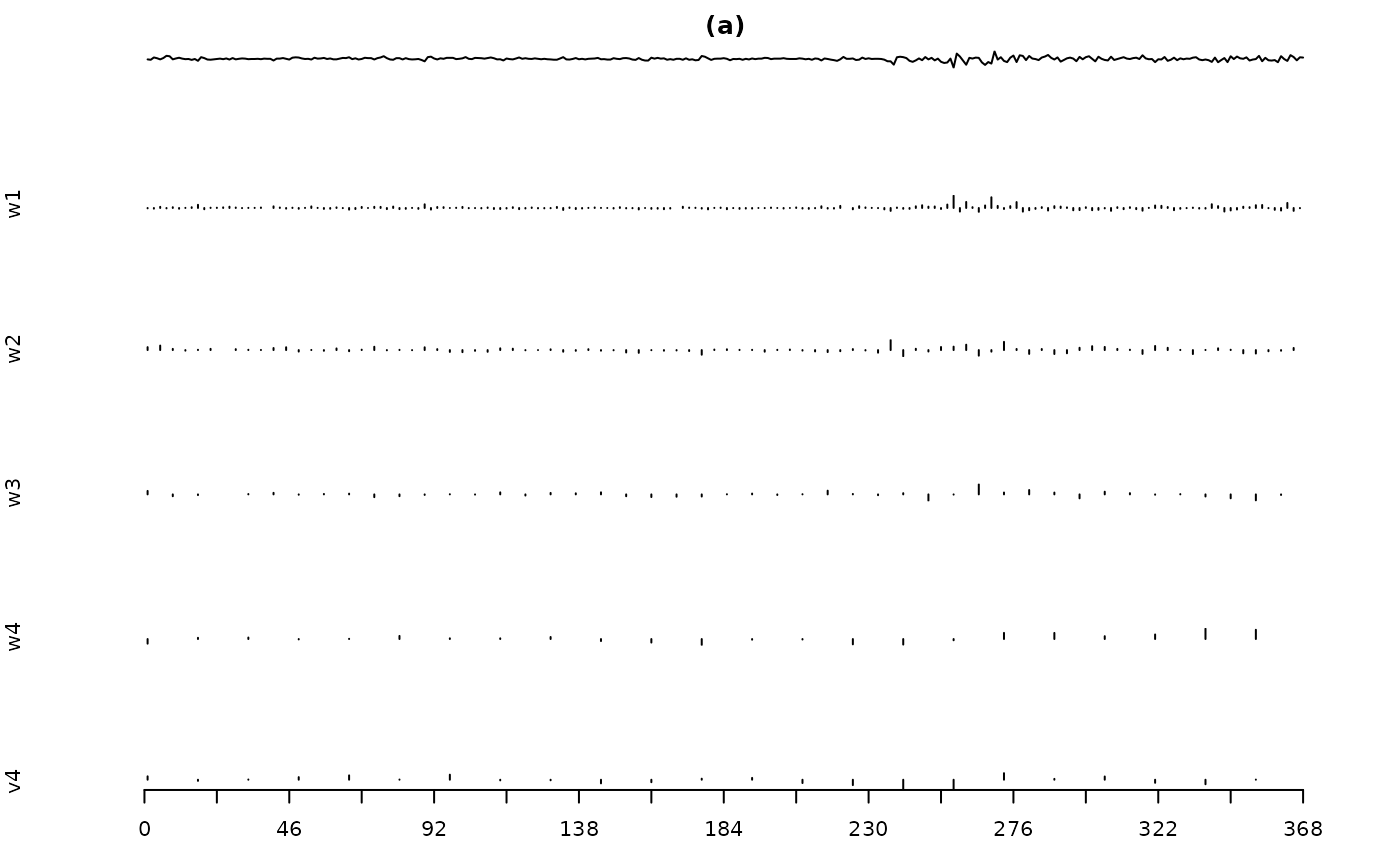
## Figures 4.17 and 4.18 in Gencay, Selcuk and Whitcher (2001).
data(ibm)
ibm.returns <- diff(log(ibm))
## Haar
ibmr.haar <- dwt(ibm.returns, "haar")
names(ibmr.haar) <- c("w1", "w2", "w3", "w4", "v4")
## plot partial Haar DWT for IBM data
par(mfcol=c(6,1), pty="m", mar=c(5-2,4,4-2,2))
plot.ts(ibm.returns, axes=FALSE, ylab="", main="(a)")
for(i in 1:4)
plot.ts(up.sample(ibmr.haar[[i]], 2^i), type="h", axes=FALSE,
ylab=names(ibmr.haar)[i])
plot.ts(up.sample(ibmr.haar$v4, 2^4), type="h", axes=FALSE,
ylab=names(ibmr.haar)[5])
axis(side=1, at=seq(0,368,by=23),
labels=c(0,"",46,"",92,"",138,"",184,"",230,"",276,"",322,"",368))
 ## LA(8)
ibmr.la8 <- dwt(ibm.returns, "la8")
names(ibmr.la8) <- c("w1", "w2", "w3", "w4", "v4")
## must shift LA(8) coefficients
ibmr.la8$w1 <- c(ibmr.la8$w1[-c(1:2)], ibmr.la8$w1[1:2])
ibmr.la8$w2 <- c(ibmr.la8$w2[-c(1:2)], ibmr.la8$w2[1:2])
for(i in names(ibmr.la8)[3:4])
ibmr.la8[[i]] <- c(ibmr.la8[[i]][-c(1:3)], ibmr.la8[[i]][1:3])
ibmr.la8$v4 <- c(ibmr.la8$v4[-c(1:2)], ibmr.la8$v4[1:2])
## plot partial LA(8) DWT for IBM data
par(mfcol=c(6,1), pty="m", mar=c(5-2,4,4-2,2))
plot.ts(ibm.returns, axes=FALSE, ylab="", main="(b)")
for(i in 1:4)
plot.ts(up.sample(ibmr.la8[[i]], 2^i), type="h", axes=FALSE,
ylab=names(ibmr.la8)[i])
plot.ts(up.sample(ibmr.la8$v4, 2^4), type="h", axes=FALSE,
ylab=names(ibmr.la8)[5])
axis(side=1, at=seq(0,368,by=23),
labels=c(0,"",46,"",92,"",138,"",184,"",230,"",276,"",322,"",368))